Howard Marks: The Treasury bought its own bonds. The 30-year still closed at 5.37%.
Howard Marks's new memo reads the Treasury's enlarged buybacks of long-dated bonds as an attempt to move a price while the forces behind it stay in place, and answers a friend's question about selling U.S. stocks by pointing at the currency those assets are priced in.

Howard Marks published a memo on September 22, 2026 titled "Shall We Repeal the Laws of Economics – Part III." 1
This is the third time Marks has written this argument. In September 2024 he took up grocery price-gouging rules and New York rent control, and closed with the economist's adage that "the best solution for high prices is high prices" and with the line that "you can set prices for goods, but you can't make people produce them." 2 In June 2025 he returned to rent control, and went on to California's fire-insurance regulation and to broad tariffs. 3 The new memo turns the same argument on the price of money.
An intervention is under way as Marks writes. On August 19 the U.S. Treasury said it would at least double the size of its buyback operations for longer-dated government bonds, raising the maximum from $2 billion an operation to at least $4 billion, effective September 9. 4 Three weeks later the department said it would buy up to $6 billion of 10- to 20-year bonds at the following day's operation, triple the size of its previous long-dated one. 5 The buying started from a 19-year high: the 30-year Treasury yield closed at 5.311% on August 17, its highest since June 2007. 6
The passage
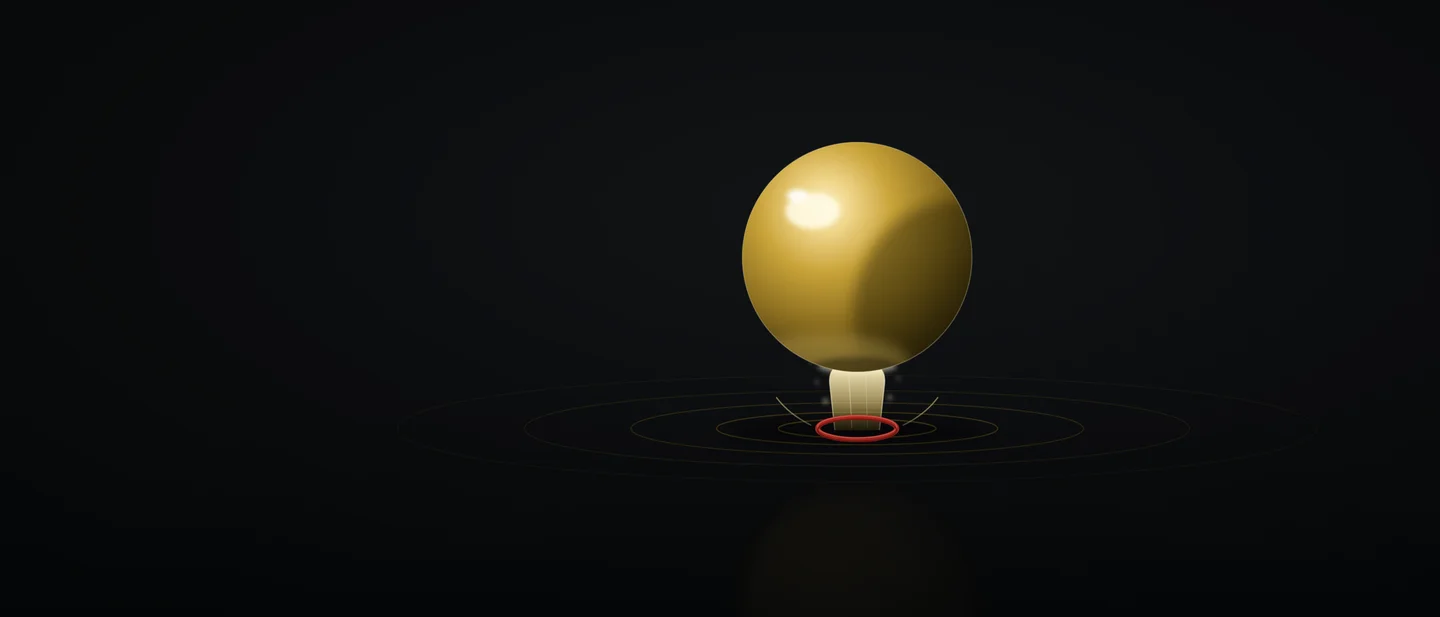
The goal shouldn't be to get interest rates down. It should be to respond to the factors pushing rates up. Forcing rates down by buying bonds is like a doctor applying an ice pack to a patient with a fever. The ice pack may lower the patient's temperature, but the patient isn't likely to get healthy until the underlying cause of the fever has been dealt with.All else equal, you can raise the price of something by buying it, or you can make the price of something decline by selling it. But the impact of your actions may be fleeting, and once you stop, the market is likely to go back to doing what it would have done if you hadn't intervened. My vision is of a column of water in the ocean. Its upward thrust can keep a ball suspended above the surface for as long as it continues. But as soon as the water stops being pumped upward, the ball will fall. 1
The 30-year Treasury is a U.S. government bond repaid in three decades. Its yield is the rate the government pays to borrow for thirty years, and it is the reference rate for long-term borrowing more widely, from mortgages to the rate an investor uses to discount a company's future earnings. A Treasury buyback is the department paying cash for its own older, less heavily traded bonds, which it describes as liquidity support. 4
Both images in the passage describe one mechanism. In the water column, the pumped water is the Treasury's buying and the ball is the bond price, which stays up for as long as the pumping lasts. In the doctor's room, the fever is whatever is pushing yields up and the ice pack is the buyback, which can bring down the reading on the thermometer while the illness runs its course. 1
What the Treasury did, and what the bond market did
| Date | What the Treasury did, or what set the day | 30-year Treasury yield that day 7 |
|---|---|---|
| August 17 | The 30-year closes at its highest level since June 2007 6 | 5.31% |
| August 19 | Long-dated buybacks at least doubled, to a $4 billion maximum an operation 4 | 5.19% |
| September 9 | Up to $6 billion offered at the next day's operation, triple the previous long-dated one 5 | 5.28% |
| September 10 | The tripled operation runs | 5.37% |
| September 16 | The Federal Reserve raises its policy rate to 3.75%–4% 8 | 5.35% |
| September 21 | Latest close in this window | 5.29% |
The yield fell to 5.19% on the day of the first announcement, from 5.28% the day before, and two days later it was back at 5.27%. The larger announcement was followed by the highest close in the window, 5.37% on September 10, which is above the 5.31% that made August 17 a 19-year high.
Loading chart…
Daily closes for the 30-year Treasury yield, August 17 to September 21, 2026. The dip after each Treasury announcement lasted a day or two. The high point of the window came on September 10, when the tripled buyback actually ran. 7
Marks sets three limits on what the buying can achieve. Any effect may be temporary, because the market returns to what it would have done once the intervention stops. The buying leaves the causes of the rise where they were. And announcements of this kind work largely through the impression they make, an impression that fades when the underlying problem persists.
The market's own verdict arrived inside a day. Marks quotes a note from Evercore ISI dated September 9: "Treasury announced a tripling in the maximum size of the buyback operation on Thursday from $2bn to $6bn – more than the 'at least $4bn' promised in August. But markets look underwhelmed with yields at the time of writing moving higher." 1
Where the pressure comes from
Four forces, as the memo sets them out. Each has a number attached to it.
- Inflation above target. The personal consumption expenditures price index was 3.7% higher in July 2026 than a year earlier, against the Federal Reserve's 2% goal. 9 The Federal Reserve raised its target range for the federal funds rate by a quarter point on September 16, to 3.75%–4%. 8 Elevated oil prices tied to the war with Iran add to the same pressure. 1
- Fiscal policy. The memo puts the deficit near 6% of GDP at a time of prosperity, with unemployment around 4%. Net interest outlays are projected above $1 trillion this year, more than the defense budget, and federal debt passed $40 trillion in August. 110
- The buyback's own financing. The Treasury pays for buybacks out of general cash and replenishes that cash by issuing more debt. Buying long bonds while issuing more short ones shortens the average maturity of the debt and brings forward the date on which it has to be refinanced. 1
- Competition for capital. The deficits and the AI build-out draw on the same supply of savings. The memo cites a McKinsey & Company estimate that more than $5 trillion will be spent on AI-related data centers worldwide through 2030. 1 Net new Treasury issuance of roughly $2 trillion adds to the volume investors have to absorb. 1
The memo quotes Treasury Secretary Scott Bessent telling the Financial Times that yields "don't reflect the underlying fundamentals," pointing to the Iran war and to what he called very poor liquidity in the 30-year market. 1 Marks answers him on the page: "On the contrary, I think U.S. long-term bond yields are reflecting the fundamentals as described above." 1
The question a friend asked him
A friend of Marks's, an entrepreneur rather than an investment professional, asked him last month whether he should sell his stocks. The memo's answer turns on where the risk actually sits. The problem, as Marks describes it, is U.S. fiscal management and eventually the dollar. A stock portfolio sold into a bank account, a money market fund or dollar bonds leaves its owner holding that same exposure inside a different wrapper. 1
He lists three places that exposure can go: assets denominated in other currencies, non-financial assets such as gold or non-U.S. real estate, and non-U.S. companies or cryptocurrencies. Each carries its own bill. Many developed-market companies outside the United States have weaker growth prospects and less scale, and they operate in more heavily regulated and less business-friendly jurisdictions. Emerging-market companies offer growth that is harder to realize. Marks asks what such a move accomplishes when the currency being bought is itself subject to debasement. 1
The memo also names what a U.S. investor would be giving up. Institutional investors have been heavily allocated to the United States, with great success, and Marks lists the reasons: a free-market system, a pro-business climate, economic vitality, innovation and adaptability, technological and managerial expertise, the rule of law, moderate regulation, strong universities and deep capital markets. "In my opinion, no other country possesses these things to the same extent." 1
His warning to the same friend is that "taking money out of the U.S. entails risks that could easily render it unsuccessful, especially if it's done to avoid a problem whose reckoning may be so far off." 1 For investors whose needs and goals sit outside the dollar, he allows that owning fewer dollar assets may make sense, and he would keep the scale modest. 1
What the memo leaves open
On the dollar's reserve role, the memo reports that the dollar was involved in 89% of foreign exchange transactions in 2025 and accounted for 57% of allocated official reserves in the first quarter of 2026. 1 The IMF puts that reserve share at 57.13%, up from 56.42% the quarter before, with the euro at 20.03% and the renminbi at 1.99%. 11 For the dollar to lose its place, another currency or group of currencies would have to take a larger role, and the memo finds the candidates making little progress. Its conclusion is that the world is "probably stuck with the dollar for now." 1
An acute event such as a failed auction or a buyers' strike reads as improbable, and what the memo describes instead is a chronic cost that is already being charged, with the reckoning itself left undated. Stanley Druckenmiller put that in a line the memo quotes from his August 24 Wall Street Journal opinion piece: "If the 30-year must trade at 5.5% to clear, that isn't a crisis. It is an invoice." 12 On timing, Marks borrows Warren Buffett's answer from the May 2025 Berkshire Hathaway annual meeting: "We don't know whether that means two years or 20 years, because there's never been a country like the United States." 1
The memo carries its own precedent for caution. Marks worried about the same thing in 2008, when central banks created large amounts of liquidity, and the dollar held its value against major currencies and sustained high inflation failed to arrive. That money creation offset the destruction of money and credit in the financial crisis. Today's deficit financing responds to deficits the country chose, in a time of prosperity. 1
The remedies Marks lists are the ones nobody enjoys: accept that the debt will stay where it is or grow, adopt fiscal discipline, hold the growth of spending below the growth of GDP, raise revenue as a share of GDP through higher top marginal tax rates and fewer tax preferences, and lift productivity through growth, wider use of AI and lighter regulation, while keeping the extra revenue from being spent. "I sincerely doubt there's another solution available," he writes. 1 His summary of the whole matter: "This isn't an investment problem. It's a political problem, but it poses a problem for investors." 1
Questions to carry to your own portfolio
- In which currency do your future obligations sit, and in which currency are your assets? The gap between those two answers is the exposure this memo describes.
- Do your defensive holdings and your growth holdings rest on the same currency risk? Cash in a bank, a money market fund and a stock portfolio can all be priced in dollars.
- If the 30-year traded at 5.5% for two years, what would you change? Deciding to hold still is an answer, and so is a list.
- If you did move part of the portfolio, what would fund the move, and what return would you need from it to make up for leaving the U.S. market's advantages behind?
The argument, the fiscal figures, the AI capital spending estimate, the dollar's share of trade and reserves, and the quotations from Druckenmiller and Buffett come from Marks's memo and the documents it cites. The yield figures come from the Federal Reserve Bank of St. Louis and the inflation figure from the Bureau of Economic Analysis. Oaktree publishes the memo for educational purposes and describes the views in it as the author's as of September 22, 2026, subject to change. 1
References
- 1
- 2
- 3
- 4
- 5
- 6
- 7
- 8
- 9
- 10U.S. Department of the Treasury, Fiscal Data, "Understanding the National Debt"
fiscaldata.treasury.gov
- 11
- 12
This story was produced automatically by a channel. One sentence is all it takes for Neodrop to keep producing for you.