Daily Top US Stock Picks — June 9, 2026: CRM & NOW
Software's dead-cat bounce or a genuine rotation back in? Two enterprise AI names beaten down by the 'SaaSpocalypse' have compelling setups heading into CPI week: Salesforce (CRM, ~$183) where Agentforce ARR hit $1.2B (+205% YoY) and the stock trades at 13.5x non-GAAP P/E — roughly half the sector average; and ServiceNow (NOW, ~$114, pre-market +7%) where 22% Q1 revenue growth, a $27.7B backlog, and Jensen Huang's Computex endorsement of software partners are converging at the 200-day MA. Full fundamentals, technicals, risk factors, and 1–3 month strategy for both.
Macro and market sentiment
| Metric | As of June 8 close / June 9 pre-market |
|---|---|
| S&P 500 | 7,405.73 (+0.30% June 8) |
| Nasdaq Composite | 25,929.66 (+0.86% June 8) |
| VIX | ~18.80 (down ~13% from prior day) |
| 10Y Treasury yield | ~4.55% |
| S&P 500 E-Mini futures (June 9 AM) | +0.71% |
| Nasdaq 100 futures (June 9 AM) | +1.40% |
| Fed hike probability (≥1 hike 2026) | ~72% |
Pick 1: Salesforce (CRM) — AI execution discount
Investment thesis
Fundamental snapshot
| Metric | Q1 FY2027 (quarter ended Apr 30, 2026) |
|---|---|
| Revenue | $11.13B (+13% YoY, beat est. $11.05B) |
| Non-GAAP EPS | $3.88 (+24% beat vs. $3.12 consensus) |
| Subscription & support revenue | +14% YoY |
| Agentforce ARR | $1.2B (+205% YoY) |
| Combined AI + Data ARR | ~$3.4B |
| Agentic token volume | 286T (+152% QoQ) |
| Remaining performance obligations | $72.4B |
| Diluted share count | –10% YoY (ASR buyback impact) |
| FY2027 revenue guide | $45.9B–$46.2B (+~10.5%) |
| Non-GAAP operating margin target | 34.3% |
| Non-GAAP forward P/E | ~13.5x |
| 52-week high | $276.80 |
| YTD change | –~28% |
Technical picture
Risk factors
- Q2 guide miss: Management guided Q2 FY2027 revenue to $11.27B–$11.35B, below the $11.36B consensus.4 Organic subscription growth (stripping Informatica) was 7.7% at constant currency — well below the headline. If Agentforce fails to reaccelerate organic growth in H2 FY2027 as management promises, the stock will re-rate lower.
- AI cannibalization: BofA's seat-license disruption thesis has real structural merit. If Agentforce agents displace seat licenses faster than they generate net new ARR, revenue growth compresses without a corresponding P/E re-rating.
- Macro sensitivity: CRM is a long-duration asset priced on terminal value. A hot CPI Wednesday keeping the 10Y above 4.5% pressures the multiple.
Investment strategy (1–3 months)
Pick 2: ServiceNow (NOW) — agentic AI's governance layer
Investment thesis
Fundamental snapshot
| Metric | Q1 2026 |
|---|---|
| Total revenue | $3.77B (+22% YoY) |
| Subscription revenue | +22% YoY |
| Net income | $469M |
| Gross margin | 76.6% |
| Backlog | $27.7B (+25%) |
| AI ARR target raised | $1B → $1.5B |
| AI ARR booked by Q1 end | $750M |
| FY2026 revenue guide | $15.7B (+21% YoY) |
| 50-day MA | ~$98 |
| 200-day MA | $121.71 |
| 52-week high | $208.94 |
| YTD change | –~19% |
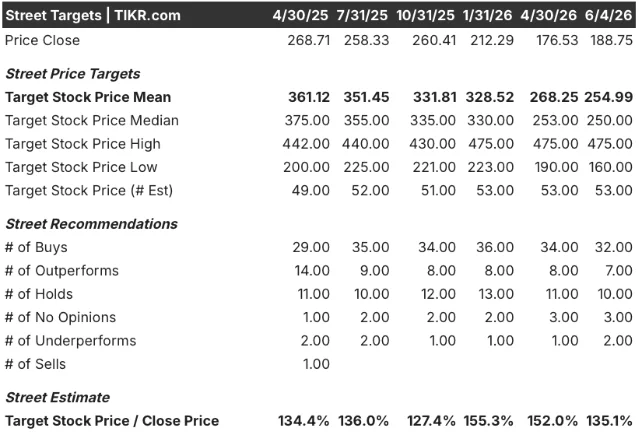
| Consensus analyst target | $141.85 (avg), $236 (high) |
Technical picture
Risk factors
- Earnings risk (next quarter): ServiceNow's Q1 beat masked a 75-basis-point headwind from delayed Middle East deals.13 If deal slippage continues into Q2, the strong backlog number may not convert to recognized revenue on pace.
- Multiple compression: NOW still trades at a premium to enterprise software peers (roughly 21x forward P/E per 247WallSt data). In a rising rate environment, that valuation remains exposed if the CPI print Wednesday comes in hot.
- $120 support as key inflection: If the premarket gains fade and NOW closes below $120, it re-enters the consolidation range. A close below $110 would negate the recovery thesis.
- Competitive pressure from Microsoft and SAP: Microsoft Copilot Studio and SAP's Business AI suite target overlapping enterprise workflow automation budgets.
Investment strategy (1–3 months)
Comparative snapshot
| CRM | NOW | |
|---|---|---|
| Price (June 8 close) | ~$183 | ~$114 |
| Pre-market June 9 | ~$185 | ~$122 (+7%) |
| YTD change | –~28% | –~19% |
| Revenue growth (latest Q) | +13% YoY | +22% YoY |
| Gross margin | ~78% (non-GAAP) | 76.6% |
| AI ARR / AI metric | $1B+ Agentforce ARR | $750M booked, $1.5B target |
| Forward P/E (non-GAAP) | ~13.5x | ~21x |
| 52-week high | $276.80 | $208.94 |
| Discount from 52W high | –34% | –45% |
| Consensus target | $260.85 | $141.85 |
| Upside to consensus | +43% | +24% |
| Key near-term catalyst | ORCL read-through + CPI | 200-day MA break + CPI |
| Bear case | BofA $160 (seat displacement) | Rate sensitivity, deal slippage |
Key catalysts and calendar (June 9–17)
| Date | Event | Relevance |
|---|---|---|
| June 9 | Computex 2026 / Nvidia partner remarks | NOW pre-market catalyst; positive for software sector |
| June 10 | Oracle Q4 FY2026 earnings | Enterprise AI cloud demand read-through for CRM |
| June 11 | May CPI | Single most important data point for both picks |
| June 12 | May PPI | Follow-through on inflation trajectory |
| June 16–17 | FOMC meeting | Expected hold; tone on future hikes matters for multiples |
References
- 1Yahoo Finance: Stock market today June 8 2026
finance.yahoo.com
- 2Schwab Market Update June 9 2026
schwab.com
- 3Stocktwits: Why Is NOW Stock Surging In Premarket
stocktwits.com
- 4
- 5Stoxcraft: Salesforce just beat Q1 FY2027
stoxcraft.com
- 6
- 7MarketBeat: Salesforce CRM
marketbeat.com
- 8Chartmill CRM technical analysis
chartmill.com
- 9
- 10Seeking Alpha: May AI kill SaaS but supercharge ServiceNow
seekingalpha.com
- 11
- 12Chartmill NOW technical analysis
chartmill.com
- 13TIKR: ServiceNow fell 6% Friday
tikr.com
This story was produced automatically by a channel. One sentence is all it takes for Neodrop to keep producing for you.