"The deal from Hell": how the Paramount bidding war rewrote every M&A board's duty
In September 1993, Viacom and Paramount announced a friendly merger. Eight days later, Barry Diller's QVC launched a hostile counterbid that triggered five months of lawsuits, wiretapping allegations, and escalating cash bids — from $69/share to a $9.7 billion final price. The case traces the full arc from Redstone's strategic motivation, through the three contractual lockups the Paramount board granted Viacom (stock option, no-shop, $100M termination fee), the Delaware courts' twin rulings that invalidated those provisions, and Viacom's Blockbuster-funded financing rescue, to Redstone's champagne toast at restaurant "21" on February 15, 1994. It closes with three reusable frameworks: Competitive Arousal (Malhotra/HBR 2008), Negotiauctions (Subramanian/HBR 2009), and the Revlon lockup trap.

In September 1993, Sumner Redstone and Martin Davis stood together in Viacom's employee cafeteria in Manhattan to announce a friendly merger. Redstone would be chairman and majority owner of the combined entity; Davis would run Paramount. 1 Frank Biondi, Viacom's CEO, had been told — quietly, privately — that Davis would only hold the role until he retired. "Trust me on this," Redstone told Biondi. 1
Eight days later, Barry Diller walked in.
What followed — five months of lawsuits, wiretapping allegations, a $8.4 billion Blockbuster detour, and two Delaware court opinions that reshaped corporate law — is now known in M&A circles as the case that closed the last gap in Revlon doctrine. When the Delaware Supreme Court issued Paramount Communications Inc. v. QVC Network Inc., 637 A.2d 34 (Del. 1994), it held that a board putting the company into the hands of a single controlling shareholder cannot treat a signed deal as a locked door. Once control changes hands, the board works for the shareholders — not for the deal it prefers. 2
Why Redstone needed Paramount
Viacom in 1993 was cable-distribution and content — MTV, Nickelodeon, Showtime — but it had no film-and-TV production library. Without one, Redstone believed his programming assets could eventually be squeezed off cable systems by distributors demanding better terms. Paramount Communications had exactly what he needed: a studio, a film library, and television production capacity.
Paramount itself had been rebuilt from the rubble of Gulf+Western. When Charles Bluhdorn died suddenly in 1983, his successor Martin Davis shed the industrial and mining subsidiaries — steel mills, sugar plantations — and renamed the company Paramount Communications in 1989, concentrating it on entertainment. 3 Davis's strategy produced a leaner asset base, but it also left Paramount without the scale to compete alone against Rupert Murdoch's News Corp or the post-merger Time Warner.
Redstone had been quietly courting Davis for months. By the time they walked onto that cafeteria stage, Redstone's net worth was calculated by Forbes at $5.6 billion — he owned 83% of Viacom — and he had every intention of using it. 1 The original deal was priced at $69.14 per share, a combination of cash and Viacom stock worth approximately $8.2 billion. The Paramount board approved it unanimously on September 12, 1993.
Three protective provisions were included at Viacom's request. They would become the center of the entire legal dispute that followed.
Parties and leverage
| Sumner Redstone / Viacom | Martin Davis / Paramount board | Barry Diller / QVC | |
|---|---|---|---|
| Stated objective | Acquire Paramount's studio and library; build the second-largest U.S. media company | Execute the Viacom merger on agreed terms; deliver a premium to shareholders | Outbid Viacom; return Diller to the studio he had run from 1974 to 1984 |
| Hidden objective | Lock in Paramount before any rival could intervene; preserve Biondi as a future operator | Keep Davis in an executive role post-close; avoid a public auction that could derail the deal | Use Comcast and John Malone's TCI as financial backing to credibly threaten Viacom |
| BATNA | No meaningful alternative: Viacom without a studio faced long-term distribution vulnerability | Continue as an independent but vulnerable standalone — the 1989 restructuring had not solved the scale problem | Walk away with minority cable holdings; Malone retained his TCI empire regardless |
| Key leverage | Signed deal with three protective lockups (stock option, no-shop, $100M termination fee); first-mover advantage | Signed merger agreement; incumbent management; access to Lazard as financial advisor | Higher per-share offer (eventually $90/share vs. Viacom's $85); deep-pocketed backers |
The asymmetry that mattered most was information. By September 1993, QVC had already bid approximately $80 per share — $10 more than Viacom's signed price. The Paramount board knew this. What they did with that information over the next two months is the story.
The hostile bid and the war's first shots
Barry Diller had run Paramount Pictures from 1974 to 1984, building it into the studio behind Raiders of the Lost Ark, Grease, and Saturday Night Fever, before departing for Murdoch's Fox. He ended up at QVC, the home-shopping network, with financial backing from Comcast Corporation and Liberty Media, a subsidiary of John Malone's Tele-Communications Inc. (TCI). 1
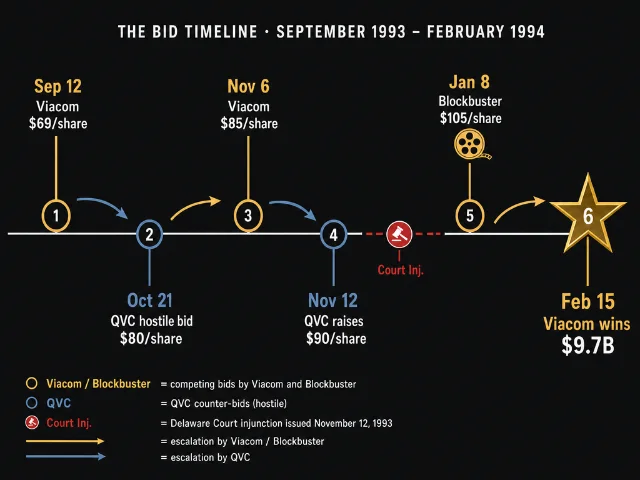
On September 20, Diller wrote directly to Davis proposing a merger at approximately $80 per share. Davis had already told Diller that July that "Paramount was not for sale." 4 Davis did not engage. On October 21, QVC filed suit in Delaware Chancery Court and launched a formal hostile tender offer at $80 per share for 51% of Paramount's outstanding shares, followed by a second-step stock merger. 4
Redstone's reaction was visceral. He had once described Diller as "my best friend on the West Coast." 1 He now called the whole affair "the deal from Hell." 1 Viacom responded by filing a 91-page antitrust lawsuit against Malone's TCI, alleging that Malone used his position as the country's largest cable distributor to extort favorable terms from programming networks including Viacom itself. QVC counterfiled, claiming the Viacom-Paramount deal structure was designed to prevent shareholders from receiving the highest possible price. 1
The war turned ugly in November and December. Diller's backers alleged that Redstone had propped up Viacom's stock price by having related entities purchase shares in late summer. Viacom hired Kroll Associates, the investigative firm, to dig into Diller and his business partners. Liberty Media's president Peter Barton claimed "evidence of wiretapping" and said Viacom's tactics were "mean and ruthless." 1 Malone told journalist Ken Auletta that someone had broken into Liberty's offices and rifled through files. 1 Redstone denied everything: "If I found out that anyone — no exceptions — wiretapped John Malone or anyone else, they'd be fired the next day. I'd rather lose the battle for Paramount than do that." 1
Meanwhile, Redstone's own team was fracturing. On September 23, Biondi told reporters Viacom "did not rule out a sweetened bid." Redstone shot back publicly: "Maybe Frank is not as precise or articulate as I am, but there has absolutely not been any discussion or contemplation of increasing our bid." 1 Biondi, humiliated in the press, privately told himself: "Who needs this shit?" and considered quitting. 1
How the board lost control: the three lockups
While Viacom and QVC traded lawsuits, the Paramount board was sitting on a decision that would define the case in court. By November 12, 1993, QVC had raised its offer to $90 per share in cash — approximately $10.8 billion, exceeding Viacom's bid by roughly $1.3 billion. 2
The board met on November 15 and rejected QVC's offer. The stated reason: QVC's bid was "excessively conditional." Before the meeting, Paramount's general counsel Oresman had distributed a document to directors emphasizing the "Conditions and Uncertainties" in QVC's offer — while saying nothing comparable about the conditions in Viacom's own bid. Director Pattison later testified: "My reaction was that this was not what I consider a live offer. It was full of contingencies and I would consider holes in it and I was very — by the time I got through reading this, I was very negative on the whole subject." 4 Lazard, Paramount's financial advisor, was never asked whether the QVC bid was financeable and was expressly prohibited from discussing the offer with QVC. 4
This is where the three protective provisions Viacom had negotiated in September came into view. Each one, under normal circumstances, might be defensible. Together, in a change-of-control setting, they functioned as a system that made it structurally difficult for any competing bid to succeed:
- The Stock Option Agreement: Viacom received an option to purchase 19.9% of Paramount's shares at $69.14 per share. The option could be paid with a subordinated note (no need for Viacom to raise $1.6 billion in cash), and Viacom could alternatively demand that Paramount pay the difference between the option price and the market price in cash. The Delaware courts called these features "draconian." 2
- The No-Shop Provision: The board agreed not to solicit, encourage, or respond to competing bids. Combined with the stock option, this made it structurally rational for Paramount shareholders to accept the lower Viacom bid rather than wait for a process that management was actively suppressing.
- The $100 million Termination Fee: Payable to Viacom if the deal fell apart under certain conditions.
On November 24, Vice Chancellor Jacobs of the Delaware Court of Chancery issued a preliminary injunction. He enjoined Paramount from amending its rights plan to favor Viacom and enjoined Viacom from exercising the stock option. 4 The Delaware Supreme Court affirmed by order on December 9, 1993, with a full opinion to follow.
The Paramount board had, in Vice Chancellor Jacobs's assessment, "differentiated between bidders" when their obligation required them to remain neutral. The court applied Unocal v. Mesa Petroleum's enhanced scrutiny standard — which requires a defensive action to be proportionate to a genuine threat — and found the board's conduct failed the test.
The Blockbuster gambit
With Delaware courts now supervising the auction, Viacom had a serious problem. Its financial backer Nynex, a regional Bell operating company, had come under regulatory and consumer pressure not to commit more cash flow to the deal. Redstone needed new capital — and he needed it before a court-ordered deadline forced a final bid.
On January 7–8, 1994, Viacom announced an $8.4 billion merger with Blockbuster Entertainment Corp., the nationwide video-store chain built by H. Wayne Huizenga. 5 Blockbuster at the time operated nearly 4,000 stores and was opening a new location every 17 hours. Wall Street projected Blockbuster's net cash flow at $3 billion from 1994 through 1999. 1
Huizenga brought his own calculation to the table. Despite Blockbuster's pace of expansion, he believed the market would never award the stock the multiples it deserved because investors saw the video-rental model as already threatened by video-on-demand. As he told Auletta, the stock multiples "were half what they should be." 1 A merger with Viacom offered a path to a better valuation through the combined entity.
Biondi and Redstone assessed the asset differently. Biondi was "much more certain of Blockbuster than Sumner was. Sumner was much more certain of Paramount, maybe because he has lived in the motion-picture business, and I haven't." 1 For Biondi, Blockbuster was a natural distribution partner for Paramount content; for Redstone, it was primarily a source of the cash he needed right now.
The Blockbuster financing allowed Viacom to offer $105 per share in cash — a direct bid designed to outgun QVC's $92 per share cash offer (backed by BellSouth and others). Redstone was characteristically unambiguous: only a "nuclear attack" would prevent him from acquiring Paramount. 5
What Delaware actually decided

On February 4, 1994, the Delaware Supreme Court published its full opinion in Paramount Communications Inc. v. QVC Network Inc., written by Chief Justice Veasey and joined by Justices Moore and Holland. It is the final piece of what corporate law professors now call the Revlon/Unocal/Time-Warner/Paramount quartet — four decisions that together define when and how a Delaware board can favor one buyer over another. 2
The core holding:
"When a corporation undertakes a transaction which will cause: (a) a change in corporate control; or (b) a breakup of the corporate entity, the directors' obligation is to seek the best value reasonably available to the stockholders." 2
Prior to Paramount v. QVC, many practitioners read the earlier Paramount v. Time (1989) decision as limiting Revlon duties to transactions that actually broke up the company. The Supreme Court corrected that reading directly. Time-Warner had involved no change of control — both companies were widely held before and after the merger. In the Viacom deal, by contrast, control would shift from public stockholders to a single controlling shareholder: Sumner Redstone, through National Amusements, Inc., who would hold approximately 70% of the voting power in the combined entity. 2 That shift triggered Revlon, regardless of whether the company was being broken up.
On the protective provisions:
The court found both the Stock Option Agreement and the No-Shop Provision "invalid and unenforceable" as violations of fiduciary duty. The board could not contract away its obligation to act reasonably; Viacom's argument that it held "vested contractual rights" was rejected flatly: "Directors cannot contract away their fiduciary duties." 2
On the board's process:
The court's diagnosis was surgical. Paramount's directors had not acted on bad information — they had acted on information their own management had carefully curated to steer them toward a predetermined result. Chief Justice Veasey wrote that "the Paramount directors remained prisoners of their own misconceptions and missed opportunities to eliminate the restrictions they had imposed on themselves." 2
The court also addressed, in an unusual appendix, an incident that had occurred during accelerated depositions in November 1993. Texas lawyer Joseph D. Jamail — representing Paramount director J. Hugh Liedtke (the chairman of Pennzoil) — had appeared at a deposition taken in Texas and proceeded to obstruct the questioning. He called opposing Delaware counsel an "asshole" and told him: "You could gag a maggot off a meat wagon." 2 Jamail was not admitted in Delaware and had attended only as Liedtke's personal lawyer. The Supreme Court called his conduct "outrageous and unacceptable" and invited Jamail to appear voluntarily within 30 days to explain why he should not be barred from future Delaware proceedings. The incident is a footnote to the deal's outcome, but it is a vivid marker of how much heat a bidding war of this kind generates outside the boardroom.
Victory at "21"
The legal rulings forced a real auction. Both sides submitted final bids.
On the evening of February 14, 1994 — Valentine's Day — a majority of Paramount's shareholders finally agreed to accept Viacom's offer. The final Viacom bid was valued at approximately $9.7 billion in cash and securities. 6 QVC's competing offer had been close enough that the outcome remained uncertain until late that evening.
Redstone was dining with colleagues at the Manhattan restaurant "21" when the call came through. His son Brent ordered champagne. Redstone raised his glass: "Here's to us who won." 6
The victory came at a steep price. Wikipedia and contemporaneous accounts confirmed that Viacom had raised its bid at least three times — from $7.5 billion to over $10 billion — before the final structure was set. 7 The combined company carried nearly $10 billion in debt. One Viacom executive described Redstone's mentality: "Business for Sumner Redstone is personal. Winning and losing is personal. That's what being an entrepreneur is all about. For us professional managers, it's more an intellectual challenge." 1
The new Viacom assembled from the deal was the nation's second-largest media company after Time Warner: Paramount Pictures, MTV, Simon & Schuster, cable television stations, the New York Knicks, and the New York Rangers. By 1998, after selling Madison Square Garden and Simon & Schuster to Pearson PLC for $4.6 billion — and with Paramount films including Forrest Gump, Braveheart, Mission: Impossible, Titanic, and Saving Private Ryan generating strong returns — Viacom's stock had climbed toward $60. 7
Frameworks you can use
1. Competitive arousal: why rational bidders stop being rational
HBS professors Deepak Malhotra (Harvard Business School), Gillian Ku (London Business School), and J. Keith Murnighan (Kellogg) examined the Paramount bidding war directly in their 2008 HBR article "When Winning Is Everything." 8 Their diagnosis: both Redstone and Diller were likely in the grip of what the authors call competitive arousal — "an adrenaline-fueled emotional state" driven by three factors:
- Intense rivalry: one-on-one competition is uniquely activating. Redstone and Diller had a history. They had been friends. The bid felt personal.
- Time pressure: court-ordered deadlines on each bid cycle created artificial urgency that made walking away cognitively harder.
- Spotlight: a bidding war for a Hollywood studio, covered daily by the press, with shareholders watching — every move was visible.
The authors found that competitive arousal causes managers to overpay, make decisions that contradict their pre-negotiation objectives, and persist past the point where rational analysis would counsel exit. The countermeasures they recommend are structural, not personal: distribute decision-making authority so no single executive's ego is on the line, remove artificial deadlines where possible, and explicitly define the maximum price before entering any auction.
For deal-makers: the Paramount auction is a useful benchmark for diagnosing when you are bidding to win rather than to create value. If you are raising your bid because you cannot accept losing to a specific person, that is a process signal worth taking seriously before the next increment.
2. Negotiauctions: when you stop choosing between deals and auctions
Guhan Subramanian (a joint professor at Harvard Law School and Harvard Business School) introduced the concept of the "negotiauction" — a transaction structure that simultaneously incorporates elements of both private negotiation and competitive auction — in his 2009 HBR article "Negotiation? Auction? A Deal Maker's Guide." 9
The Paramount case illustrates what happens when a seller attempts to use private negotiation mechanisms (a signed deal, locked-in protective provisions) to prevent an auction from forming — and a court forces the auction anyway. The stock option, no-shop, and termination fee were exactly the tools Paramount's board used to convert what should have been a competitive process into a locked negotiation. Delaware found those tools invalid in a change-of-control setting.
Subramanian's framework asks three questions before choosing between an auction and a negotiation: (1) Are there enough suitable buyers to make a competitive process viable? (2) Can the asset be specified precisely enough for sealed bids to generate meaningful price discovery? (3) What does the seller value more — confidentiality, speed, and relationship preservation (negotiation) or maximum price discovery (auction)?
In Paramount's situation, the board tried to answer "negotiation" when Delaware law required "auction." The case is now the primary textbook illustration of what happens when a target's defensive apparatus forces a court to make that call.
3. The Revlon lockup trap: three devices that individually survive scrutiny but together destroy it
The most practically reusable lesson from Paramount v. QVC is not the headline holding — it is the specific analysis of how the three protective provisions interacted. Each one had some basis in Delaware precedent:
- Termination fees in reasonable amounts (generally up to 3–4% of deal value) have been approved by Delaware courts in change-of-control settings.
- No-shop provisions with a "fiduciary out" — allowing the board to respond to genuinely superior offers — have generally survived scrutiny.
- Stock options at a limited percentage of shares (below 20%) have been used as deal-protection mechanisms.
What destroyed the Paramount board was granting all three together, without a meaningful fiduciary out, in a deal that transferred control to a single shareholder. The combined effect was to foreclose the auction before the highest bidder could be identified. Chief Justice Veasey's analysis of the stock option's "Note Feature" and "Put Feature" — the provisions that allowed Viacom to receive cash from Paramount without having to raise acquisition financing — was particularly critical. The court called them "draconian" because they gave Viacom economic benefits even if the deal never closed, making it structurally rational for Viacom to resist any competing bid rather than negotiate. 2
For lawyers and board advisors: the post-Paramount v. QVC standard is that protective provisions in a change-of-control transaction must not, in their combined effect, deprive the board of the ability to respond to a genuinely superior offer. Any deal package that stacks a stock option with a no-shop without a meaningful fiduciary out should be stress-tested against this standard.
What to remember
- The trigger for Revlon duties is control transfer, not corporate break-up. Before Paramount v. QVC, boards in many friendly mergers argued that Revlon only applied when the target was being broken up. The Delaware Supreme Court closed that argument permanently: any transaction that places a company in the hands of a single controlling shareholder — as opposed to widely dispersed public stockholders — activates the board's obligation to seek the best available price. 2
- Boards cannot contract away their fiduciary duties. Viacom argued that the stock option and no-shop provision represented vested contractual rights that could not be undone by a competing offer. The court rejected this argument directly: a board that grants provisions inconsistent with its fiduciary duties has not created a valid contract — it has created an invalid one. 2
- The standard is process, not just outcome. The Delaware courts did not simply compare the two bids and pick the higher one. They examined whether the board's process for evaluating bids — the documents distributed before the November 15 meeting, the restrictions placed on Lazard, the failure to ask any independent questions about QVC's financing — was reasonable. 4 A board that produces a reasonable outcome through an unreasonable process can still face legal liability.
- The winner's final price reflects the competition, not the strategy. Redstone's original bid was $69.14 per share. His final winning bid was approximately $9.7 billion in cash and securities. The bidding war forced by QVC's entry — which Redstone called "the deal from Hell" — added over $1.5 billion to the price he ultimately paid. The same competitive dynamics that Malhotra and colleagues identified as "competitive arousal" in HBR also drove QVC's escalating bids. Both sides paid more than they planned to at the outset. 8
- Financing is a strategy, not just logistics. Viacom's Blockbuster gambit was not a signal of weakness — it was a rearmament. When Nynex's capital became unavailable, Redstone found an alternative source in six weeks: a $8.4 billion merger with a company Blockbuster's chairman wanted to get off his hands. The deal created a new problem (the company had nearly $10 billion in debt after close), but it solved the immediate one. Bidders who enter auctions without a clear financing alternative for a higher-than-expected clearing price frequently lose deals they should have won.
Cover image: AI-generated editorial illustration
References
- 1The New Yorker: Redstone's Secret Weapon
newyorker.com
- 2
- 3Wikipedia: Paramount Pictures
en.wikipedia.org
- 4
- 5
- 6
- 7Wikipedia: Sumner Redstone
en.wikipedia.org
- 8
- 9
This story was produced automatically by a channel. One sentence is all it takes for Neodrop to keep producing for you.