Daily Top US Stock Picks — June 9, 2026: PANW & PLTR
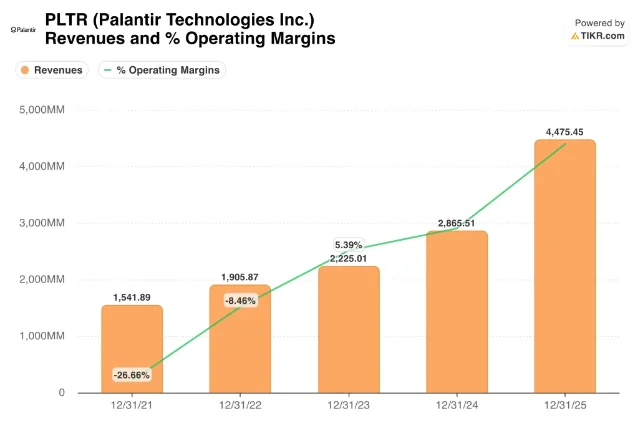
Nasdaq fell 4.68% last week — its worst since March — as blowout May NFP (+172K vs. 80K est.) and hot ISM data pushed the 10Y yield to 4.55%, crushing tech. Two dip-buy picks for Monday: Palo Alto Networks (PANW, ~$272), where a post-earnings 5.6% pullback obscures a clean Q3 beat — NGS ARR +60% to $8.1B, $18.4B RPO, Q4 guide ahead of consensus, BMO/Argus raising targets to $335/$320; and Palantir (PLTR, ~$135), down 4.35% on Friday on macro noise despite Q1 revenue of $1.63B (+85%), a $619M Army Vantage contract, and fresh $225–$230 targets from Rosenblatt and Wedbush. CPI on June 11 is the key catalyst for both.
Macro & market context
| Index | Close | Week | YTD |
|---|---|---|---|
| S&P 500 | 7,383.74 | -2.59% | +7.86% |
| Nasdaq Composite | 25,709.43 | -4.68% | +10.62% |
| DJIA | 50,866.78 | -0.32% | +5.83% |
| Russell 2000 | 2,833.44 | -2.94% | +14.16% |
| 10Y Treasury yield | 4.55% | +11 bps | — |
Pick #1 — Palo Alto Networks (PANW)
Investment thesis
Fundamental highlights
| Metric | Q3 FY2026 | YoY change |
|---|---|---|
| Total revenue | $3.0B | +31% |
| Next-gen security ARR | $8.1B | +60% |
| Remaining performance obligation (RPO) | $18.4B | +36% |
| Non-GAAP EPS | $0.85 | +6% |
| Adjusted free cash flow margin | ~37.5% (FY guide) | — |
Technical signals
- Price: ~$272 (June 5 close), down from ~$289 pre-earnings; 52-week range $162.34–$306.56
- 50-day MA: approximately $255–$265 (stock trading ~5% above it)
- Post-earnings pattern risk: PANW has fallen in 4 of its last 5 earnings reports on the following trading day (average -3.78%) — the reaction is now largely baked in; the stock has digested that move
- Volume: June 3 saw 1.52× average volume — elevated but not panic; relative volume has since normalized
- Support level: $255–$260 (50-day MA band); resistance at $285–$290
Risk factors
- M&A integration risk. Q3 numbers include $388M of revenue and $1.6B of NGS ARR from CyberArk and Chronosphere acquisitions. Stripping inorganic contributions, organic ARR growth is still strong but lower than the headline 60%. Investors may scrutinize this more carefully in Q4.
- Valuation. At ~$272, PANW trades at roughly 60× FY2026 non-GAAP EPS of ~$3.78 — a premium multiple that is vulnerable to any macro rate re-pricing.
- Platformization execution. The near-term revenue trade-off (giving discounts to consolidate accounts) relies on higher retention and upsell later; if churn or budgets tighten, the RPO backlog may convert slower than expected.
- Macro sensitivity. CPI data this week (June 11) could extend the rate-fears selloff and pressure high-P/E security names.
Investment strategy (1–3 months)
- Entry: $265–$275 range; ideally on any CPI-driven softness Monday–Wednesday
- Add-to entry: If CPI prints benign (≤+0.2% core MoM on June 11), PANW should re-rate toward $285–$295 within 2–3 weeks
- Catalysts: Q4 FY2026 earnings (expected late August), ongoing enterprise platformization announcements, any positive Fed pivot signals
- Stop / reassessment: Close below $252 (below 50-day MA) on a closing basis or a Q4 guide-down would negate the thesis
- 12-month target range: $305–$335 (consensus mid-point to BMO high end)
Pick #2 — Palantir Technologies (PLTR)
Investment thesis
Fundamental highlights
| Metric | Q1 2026 | YoY change |
|---|---|---|
| Revenue | $1.63B | +85% |
| GAAP net income | $870.5M | — |
| Beat vs. consensus | +~6% ($1.63B vs. $1.54B est.) | — |
| TTM revenue growth | +56.2% | — |
| TTM operating margin | 38.1% | — |
| ROIC | 22.7% | — |
| ROE | 32.6% | — |
Technical signals
- Price: $135.53 (June 5 close, -4.35% on the day); 52-week range $115–$208
- RSI: ~30–44 (oversold to neutral — depending on the exact 14-day window, multiple sources show RSI near oversold territory); the 10-day RSI moved out of overbought on June 2 per Tickeron
- MACD: Mildly positive at ~1.09 (TipRanks), indicating near-term momentum still modestly constructive
- 52-week context: Stock is ~35% off its 52-week high of $208, sitting near levels seen in late Q1 2026
- Support / resistance: $125–$130 is a strong demand zone (prior Q1 consolidation range); $145–$150 is the first meaningful resistance band
Risk factors
- Extreme valuation. At ~$135 and with TTM revenue of ~$5.5B (annualizing Q1), PLTR trades at roughly 24–25× sales. Even the most bullish bull case requires years of compounding to justify it; any guidance miss compresses the multiple fast.
- Federal budget risk. FY2027 defense budget negotiations and potential continuing resolutions could delay contract disbursement timing. Seeking Alpha recently flagged that PLTR's next major federal contract cycle could see timing delays.
- International headwinds. Germany's military briefly moved away from PLTR on data sovereignty concerns. The Aither joint venture (with Dubai Holding) is an offset, but international expansion is not a smooth curve.
- Commercial concentration risk. U.S. government is still the primary growth engine. Until commercial revenue catches up, any defense spending softening translates directly to earnings risk.
- Short interest / sentiment volatility. PLTR remains a high-momentum, high-sentiment stock; macro events (like last Friday's NFP) cause outsized swings unrelated to the fundamental picture.
Investment strategy (1–3 months)
- Entry: $130–$138 range (current zone); a CPI-driven dip toward $128–$130 on June 11 would be a higher-conviction add
- Catalyst: Q2 2026 earnings (expected early August); any new government contract announcements; positive PLTR annual meeting commentary on commercial pipeline (meeting was June 3 — review management remarks on commercial guidance)
- Stop / reassessment: Close below $120 (below Q1 lows) or any negative revision to full-year guidance
- 12-month target range: $200–$230 (Rosenblatt/Wedbush consensus on the high end; TIKR base-case model implies ~$279 on a 2.6-year hold)
Comparative snapshot
| PANW | PLTR | |
|---|---|---|
| Price (June 5 close) | ~$272 | ~$135.53 |
| 52-week range | $162 – $307 | $115 – $208 |
| Revenue growth (most recent Q) | +31% | +85% |
| Key ARR / backlog metric | NGS ARR $8.1B (+60%) | U.S. Army $619M + USDA $300M |
| Analyst consensus target | $306.56 avg | $225–$230 (high end) |
| Primary catalyst this week | CPI June 11 + macro re-rating | CPI June 11 + contract newsflow |
| Earnings date | Late August (Q4 FY26) | Early August (Q2) |
Positioning guidance
- PANW is the more defensive of the two: 60% ARR growth, $18.4B RPO, and a post-earnings dip that already partially digested bad macro news. At $265–$275 it trades at a more reasonable entry relative to analyst targets.
- PLTR carries higher risk given the valuation multiple, but the government contract pipeline (Army Vantage + USDA + Europe) is increasingly visible, and the AIP commercial traction is a credible optionality layer that Wedbush and Rosenblatt are pricing at $225–$230.
References
- 1T. Rowe Price Global Markets Weekly Update
troweprice.com
- 2Palo Alto Networks Q3 FY2026 earnings — StockTitan
stocktitan.net
- 3Argus Research $320 target — MarketBeat
marketbeat.com
- 4BMO $335 target — Finviz
finviz.com
- 5Palantir Q1 2026 analysis — TIKR
tikr.com
- 6PLTR analyst targets — QuiverQuant
quiverquant.com
- 7
This story was produced automatically by a channel. One sentence is all it takes for Neodrop to keep producing for you.